Payments
The Payments module covers the CNB’s innovative projects and research related to the future of payments. These mainly include the development of the instant payment system and efforts to promote the broadest practical use of this advanced infrastructure – for example, by removing barriers or involving additional participants.
Possibilities for linking the CERTIS payment system with instant payment systems in Europe and elsewhere are being analysed, and discussions are also under way on the more distant future, when the current system will need to be replaced by another solution. The Payments module also covers topics such as digitalisation and tokenisation of money – including central bank digital currencies (CBDCs), which are currently the subject of intense international expert debate, as well as stablecoins and tokenised deposits and their use in cross-border payments.
Development of instant payments
Instant payments enable one-off transfers in koruna between clients of Czech banks within just a few seconds.
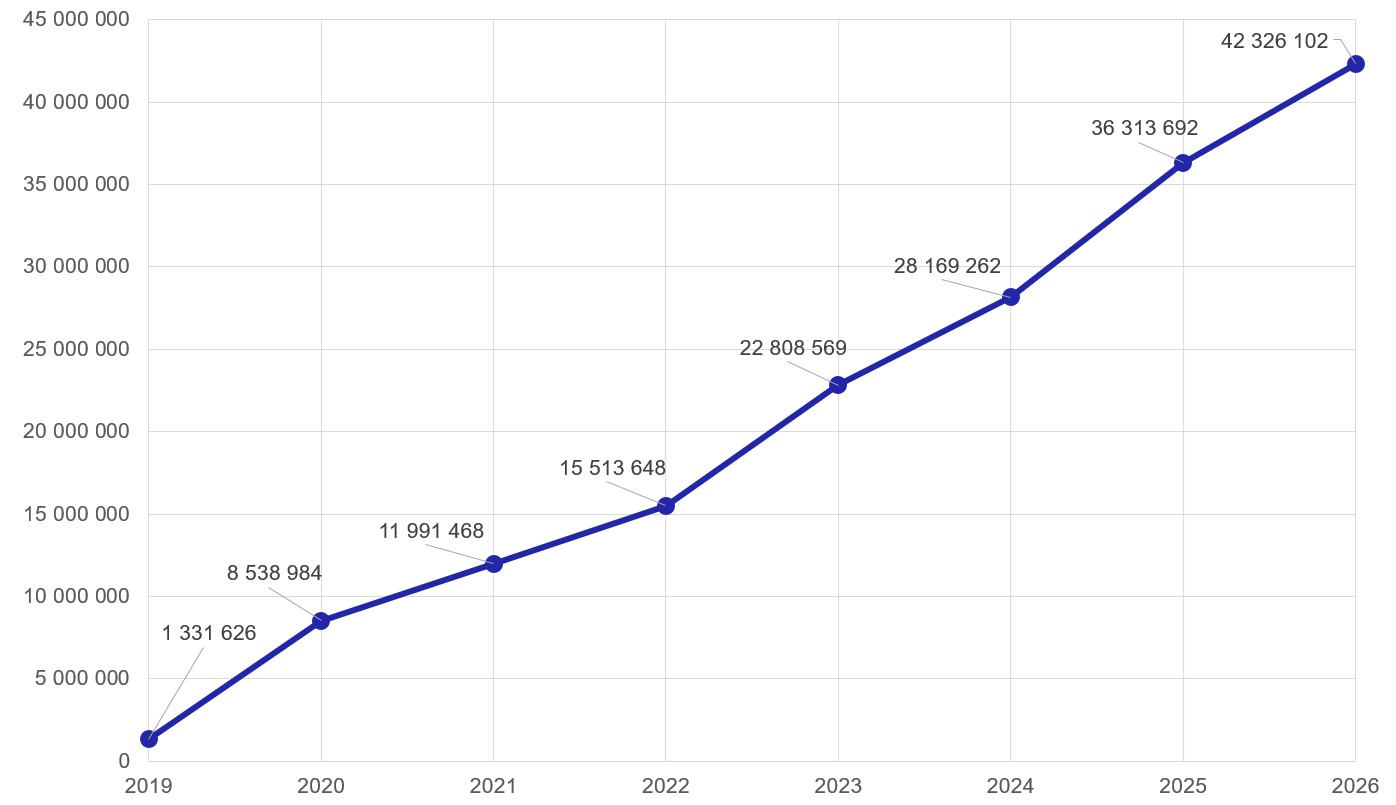
The Czech National Bank, which operates the system, currently processes around 42 million of these instant transactions each month (data for October 2026). A key factor behind this growth is the wide availability of the service, which is now accessible to 99% of bank clients on the Czech market who are consumers. Instant payments are available 24 hours a day, seven days a week.
| 2019 | 2020 | 2021 | 2022 | 2023* | 2024 | 2025** | 2026 | |
|---|---|---|---|---|---|---|---|---|
| Market coverage of instant payments | 41% | 87% | 90% | 91% | 90% | 90% | 99% | 99% |
* A one-percentage-point drop due to the collapse of Sberbank
** As of 9 April 2025
Instant payments have become the standard. The money arrives within seconds – at night, at weekends, even on public holidays. “Only a few years ago, payments took two days or more. We have made great progress – we have built the instant payments infrastructure and continue to invest in it,” said CNB Governor Aleš Michl.
Instant payments are rapidly growing in popularity among individuals and businesses. They now account for 46% of all interbank credit transfers made by clients – compared to only around one-third two years ago. CNB statistics show that while the number of standard credit transfers is flat or even falling slightly, the number of instant payments is rising steadily.
Chart – Monthly number of instant payments
(October of given year)
Instant payments are increasingly being adopted by retailers, who use them as a lower-cost alternative to card payments. The potential for future growth is immense, given the rapid pace of technological advancement – alongside cards and cash, retailers are increasingly offering customers new payment solutions based on instant payments, using QR codes, NFC technology, or third-party payment initiation under the Payment Services Directive (PSD2).
Growing competition in the payments sector benefits the entire Czech economy. For customers, it means greater convenience and a wider choice of payment instruments. For retailers, it means savings on card transaction fees and cash handling costs.
The CNB continues to work intensively on the further development and use of instant payments, including support for the necessary changes in the payment infrastructure and cooperation with the banking sector on their broader application in practice, while strengthening security standards and the resilience of the payment system.
The CNB therefore took over responsibility for the rules governing instant payments during 2025 and subsequently launched the National Payments Forum in June 2026. The Forum serves as a platform for structured discussions with all stakeholders on the functioning and further development of payments in the Czech Republic.
The aim is to increase competition and security in payments through open and constructive dialogue. Two working groups have been established, one focusing on instant payments and the other on payment fraud prevention. QR codes (whose standard needs to be modernised) and the initiation of instant payments through standardised links to banks’ mobile applications have been identified as the first areas for improvement. In the area of security, work is under way to introduce payee verification for domestic koruna payments and to improve communication both with the public and between the public and private sectors. Further information is available on the National Payments Forum web page (in Czech only).
Instant payments for cross-border and non-bank payment service providers
The CNB seeks to promote competition in payments by making the CERTIS payment system accessible to all interested parties, to the greatest extent permitted by regulation. At the same time, it takes into account the security of CERTIS. Cross-border participation by banks from the European Union, including those that do not have a registered office or branch in the Czech Republic, has been possible for several years. Instant payments have been used in this way by the Maltese bank Multitude Bank, p.l.c. since 2023.
For more than a decade, the CNB also advocated for EU legislation to allow non-bank payment service providers to participate in payment systems operated by central banks. This was achieved in 2024. The CNB subsequently made CERTIS available to them in May 2025, the earliest date possible permitted under the legislation.
At the start of 2026, CERTIS welcomed its first foreign non-bank payment service provider, followed on 16 March 2026 by the first domestic one. Negotiations on participation are under way with several other non-bank payment service providers.
Instant payments for the state
As the bank of the state, the CNB – which maintains accounts for ministries, municipalities and regional authorities, as well as, for example, the tax authorities and health insurers – also started accepting instant payments in November 2025. It is now thus possible to pay taxes, fees, insurance contributions and other state contributions within seconds – on weekdays, weekends and public holidays, day and night. “We are responding to the needs of the public and businesses, making it easier and faster for them to meet their obligations to various public authorities and institutions,” said CNB Bank Board member Karina Kubelková.
Bulk instant payments
As regards other projects in this area, the CNB is preparing – in cooperation with commercial banks – a solution enabling rapid processing of bulk payments (ASAP payments).
ASAP payments are a new type of interbank payment intended primarily for business and corporate clients. The aim is to extend the benefits of fast payments to clients who submit large numbers of payments in batches, while enabling these payments to be processed around the clock.
Unlike instant payments, which are used mainly by retail clients for individual transactions, ASAP payments allow entire batches of payments submitted by corporate clients to be processed. A single batch can contain more than 40,000 payment orders submitted simultaneously. Businesses will therefore be able to continue submitting payments in the way they are accustomed to, while also benefiting from faster processing.
ASAP payments will be processed continuously, 24 hours a day, 7 days a week, 365 days a year, and subsequently forwarded to the recipients’ banks at regular one-minute intervals. They thus combine the simplicity of batch payment submission with the speed and around-the-clock availability of modern interbank payments.
More about instant payments
- All you need to know about CNB instant payments
- Detailed information on the CERTIS interbank payment system, including statistics and a list of participants
- Instant payments in Czechia: Adoption and future trends (I. Trubelík, T. Karhánek, S. Malovaná, A. Michl) – article on the development of the instant payments system in the Czech Republic.
Future of payments
Interlinking of instant payment systems
A number of instant payment systems have already been interlinked bilaterally in Southeast Asia, where the Monetary Authority of Singapore (MAS) has been a pioneer. Users in Singapore can now send instant payments to the Philippines, India, Indonesia, Malaysia and Thailand. MAS, together with the Bank for International Settlements, is also the driving force behind the Nexus project, which should provide a global infrastructure for connecting all existing instant payment systems in the future. The Nexus Global Payments scheme and infrastructure are currently being developed. The ECB is also exploring the possibility to interlink the TARGET Instant Payment Settlement (TIPS) service with the Nexus scheme.
In Europe, several non-euro area countries have already migrated to the Eurosystem’s instant payment infrastructure, TIPS, or are currently doing so. TIPS already settles instant payments in Swedish krona and Danish krone, and is expected to process Norwegian krone payments from 2028, followed later by Icelandic króna payments. The CNB has thoroughly examined the reasons behind the decisions of the Danish and Swedish central banks to join TIPS, as well as the costs and benefits of this step. The analyses concluded that, for now, it makes more sense for the CNB to focus on further developing the CERTIS system. Instant koruna and euro payments can be interlinked more quickly by using the newly launched OCT Inst scheme for cross-border euro instant payments and by enabling instant koruna payments in CERTIS for non-bank providers specialising in foreign exchange transactions.
Digitalisation of money
The Czech National Bank began to take an interest in the topic of digital money – whether issued by central banks, stablecoins on public blockchains, or the tokenisation of commercial bank money – as early as 2017. In February 2021, a working group on CBDCs was established, with all relevant CNB organisational units represented. Its main task was to monitor and analyse ongoing developments in the area of CBDCs, focusing on the potential implications for the CNB and the Czech Republic – including analyses of whether, and under what conditions, it would be reasonable to consider the issuance of a CBDC by the Czech National Bank.
Central bank digital currencies can generally be defined as digital money that represents a direct claim of the holder on the central bank. They are denominated in the official unit of account of the respective country (in the case of the Czech Republic, the koruna). CBDCs are a new, digital form of money issued by central banks. Like today’s cash, they can be used as a medium of exchange (for payments) and a store of value (for saving).
CBDCs therefore essentially extend access to central bank non-cash money. At present, this access is available mainly to commercial banks, in the form of money held in accounts at the central bank. In the case of a retail (or universal) CBDC, such access would also be granted to other entities – such as individuals and businesses.
Of the major central banks, only the European Central Bank (ECB) is actively working on a digital currency project. In October 2025, it announced the completion of a two-year preparation phase for the digital euro, with pilot testing potentially starting in 2027, provided that the necessary legislation is approved.
The CNB Bank Board has not yet taken any decision regarding the possible issuance of a Czech CBDC. According to representatives of the working group, any potential introduction of central bank digital money in the Czech Republic should be preceded by a thorough assessment of its necessity and added value under the specific domestic conditions, as well as a public debate on such a step. A necessary precondition for the CNB to issue CBDC would be a corresponding change in legislation, as the current legal framework does not allow for the issuance of CBDCs in the Czech Republic.
CBDCs and related topics: CNB publications and commentary
A comprehensive overview of CNB outputs addressing the benefits, potential risks, and potential introduction of a CBDC in the Czech Republic:
6 September 2025 – Digital euro: The wallet of the future?, J. Kubíček – commentary (in Czech only)
6 March 2025 – Central bank digital currencies (pdf, 906 kB), M. Vodrážka – presentation (in Czech only)
8 November 2022 – The CNB publishes a document on central bank digital currency, produced by a CNB working group on CBDC. Central bank digital currency (pdf, 1 MB) – publication (in Czech only)
17 May 2022 – CNB digital currency – The future of the koruna? Still more questions than answers, O. Dědek (pdf, 788 kB) – presentation (in Czech only)
16 December 2020 – Central bank digital currency (CBDC), V. Molnár – cnBlog (in Czech only)